
Three years ago, I was making a fairly average salary, living in a fairly average apartment, and carrying just over $20,000 in debt across two credit cards and a car loan. No inheritance windfall, no side hustle that suddenly took off, no drastic salary jump. Just a plan, a lot of unglamorous months, and a decision to stop pretending the debt would sort itself out.
Here’s what actually worked, in the order I did it.
Step 1: I Stopped Avoiding the Number
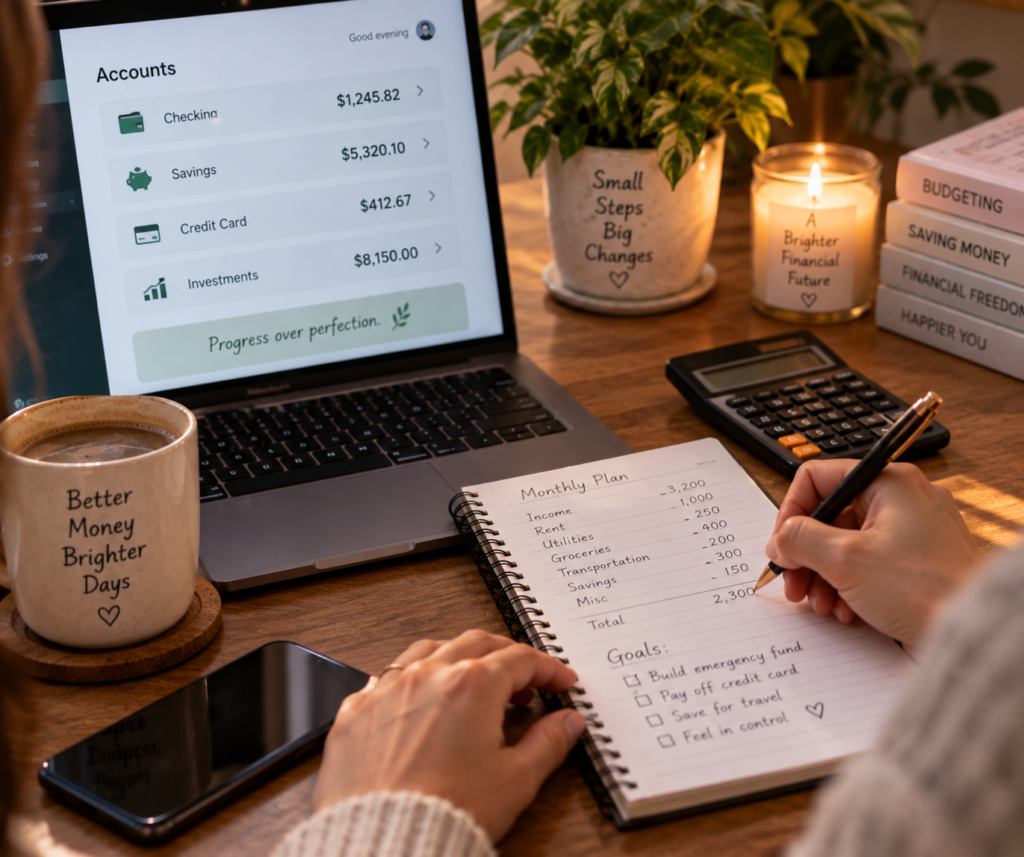
For almost a year, I genuinely didn’t know my total debt. I knew each individual balance, but I’d never added them together, because some part of me didn’t want to see the full number. When I finally did the math, it was $20,347. Seeing it in one place was uncomfortable, but it was also the first moment the problem felt solvable instead of just scary.
I wrote down every balance, every interest rate, and every minimum payment on one page. That page became the map for everything that followed.
Step 2: I Picked the Avalanche Method
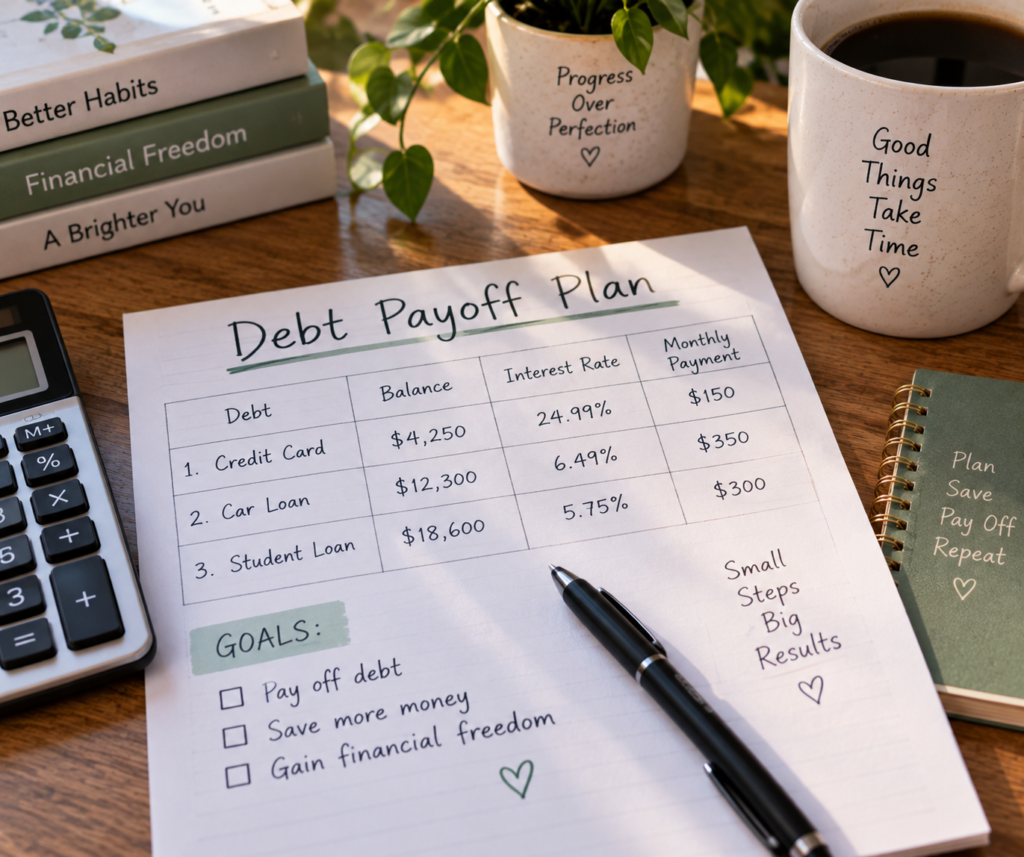
There are two popular strategies for paying off multiple debts: the snowball method, where you pay off the smallest balance first for quick wins, and the avalanche method, where you pay off the highest interest rate first to save the most money. I went with avalanche, because one of my credit cards had a brutal 24% interest rate that was quietly costing me more every month than I wanted to admit.
I kept making minimum payments on everything else and threw every extra dollar at that one card first. It took about seven months to clear it, and the moment it was gone, my other payments started moving faster too, since I redirected that payment amount to the next-highest balance.
Step 3: I Found Money I Didn’t Know I Had
I went through three months of statements line by line and found around $180 a month in subscriptions and memberships I’d forgotten I was paying for. A gym I hadn’t visited in months, a streaming service I didn’t watch, a meal kit I’d meant to cancel. None of it was glamorous, but $180 a month redirected straight to debt added up to over $2,000 a year without changing my actual lifestyle in any way I noticed day to day.
I also renegotiated my car insurance and phone plan, which took maybe two hours total and saved another $50 a month.
Step 4: I Gave Every Dollar a Job
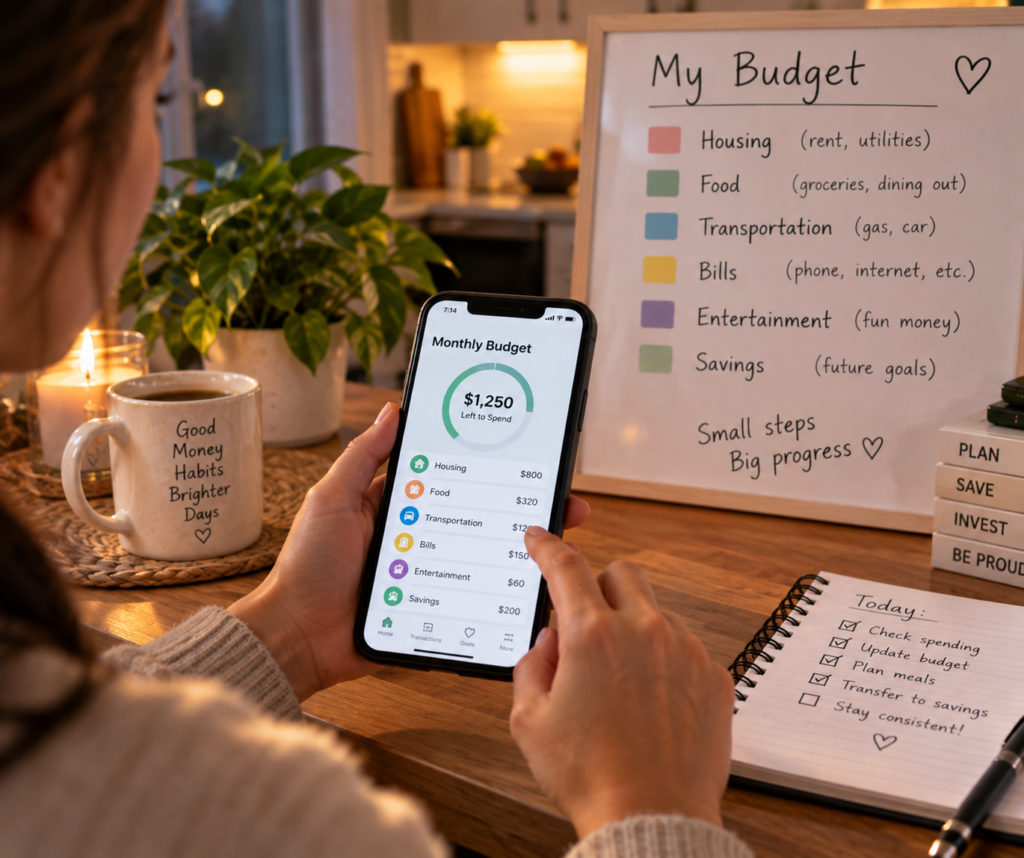
Instead of a vague goal of “spend less,” I started assigning every paycheck a specific job the moment it landed: rent, groceries, minimum payments, one extra debt payment, and a small amount for actual fun so I wouldn’t feel deprived and quit. That last part mattered more than I expected. Cutting out all enjoyment for years isn’t sustainable for most people, myself included, and I needed this to last.
Some months the extra debt payment was $400. Other months, when money was tighter, it was $60. The amount fluctuated, but the habit of paying something extra every single month never did.
Step 5: I Tracked Progress Somewhere I’d Actually See It
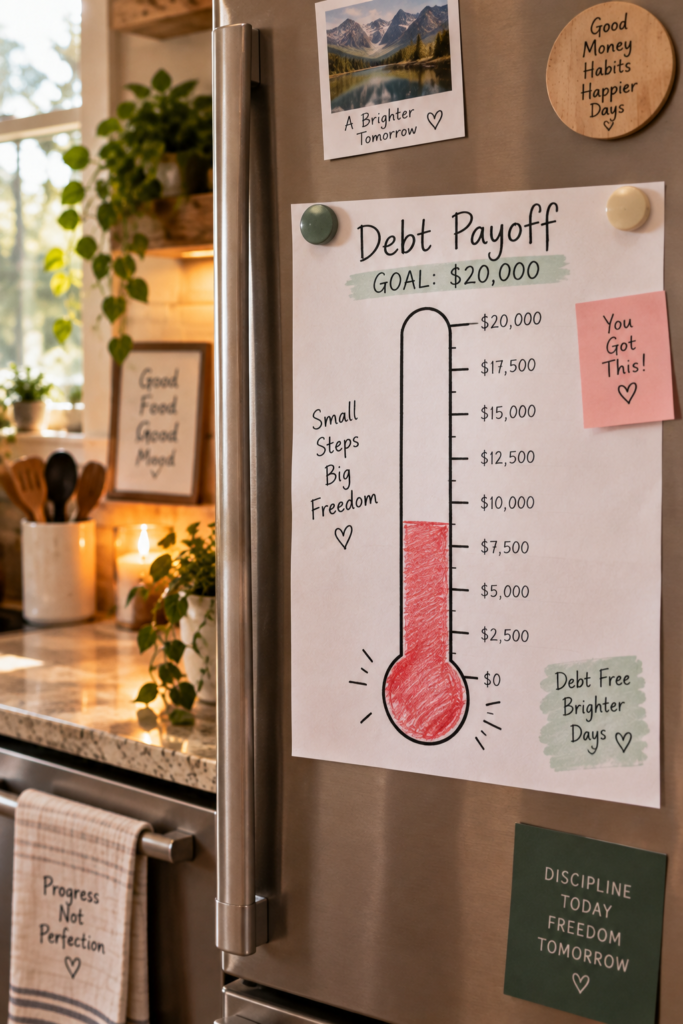
I taped a simple progress chart to my fridge, a basic thermometer drawing that I colored in as the total debt went down. It sounds almost too simple to matter, but seeing that visual every single day, especially on the months progress felt slow, kept the goal in front of me instead of buried in a spreadsheet I only opened once a month.
Step 6: I Treated Setbacks as Detours, Not Failures
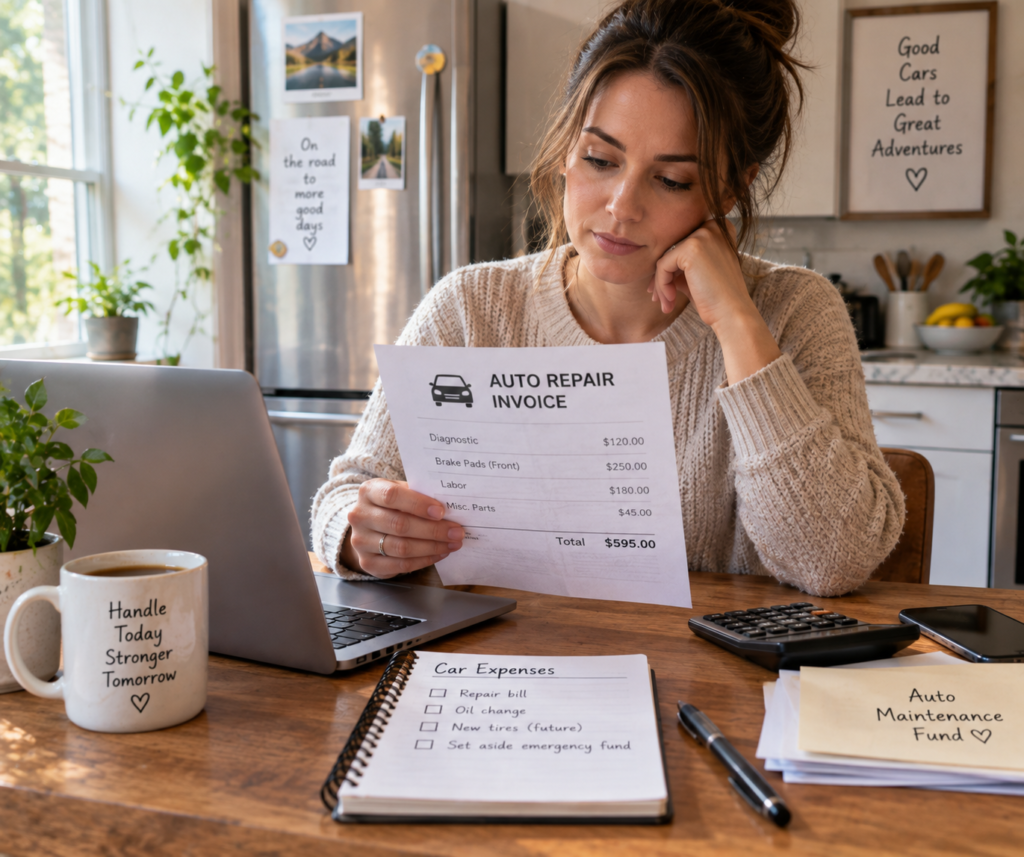
About a year and a half in, my car needed an unexpected $900 repair. Old me would have seen that as the plan falling apart. This time, I paused extra debt payments for two months to cover it in cash instead of putting it on a card, then picked the plan back up exactly where I’d left off. The debt payoff took two months longer than originally planned, and that was fine. The goal was progress, not a perfect timeline.
Where I Landed ?
It took just under three years to go from $20,347 to zero, on a salary that never dramatically changed. What changed was that I stopped treating the debt as a background stressor and started treating it as a project with a plan, a number to check on, and small consistent actions every month.
If you’re staring at your own number right now, feeling like it’s too big to make a dent in, I’d tell you what I wish someone had told me: it doesn’t take a big salary or a big move to fix this. It takes seeing the real number, picking one method, and giving it more months than feels comfortable. The math does the rest.

I’m Grayson Watson, your frugal companion and the brain behind this money-saving extravaganza. Strap yourself in, because we’re about to embark on a wallet-friendly adventure like no other. Learn More!